Crypto Debit Cards Gain Traction, But Consumers Should Weigh Risks and Fees
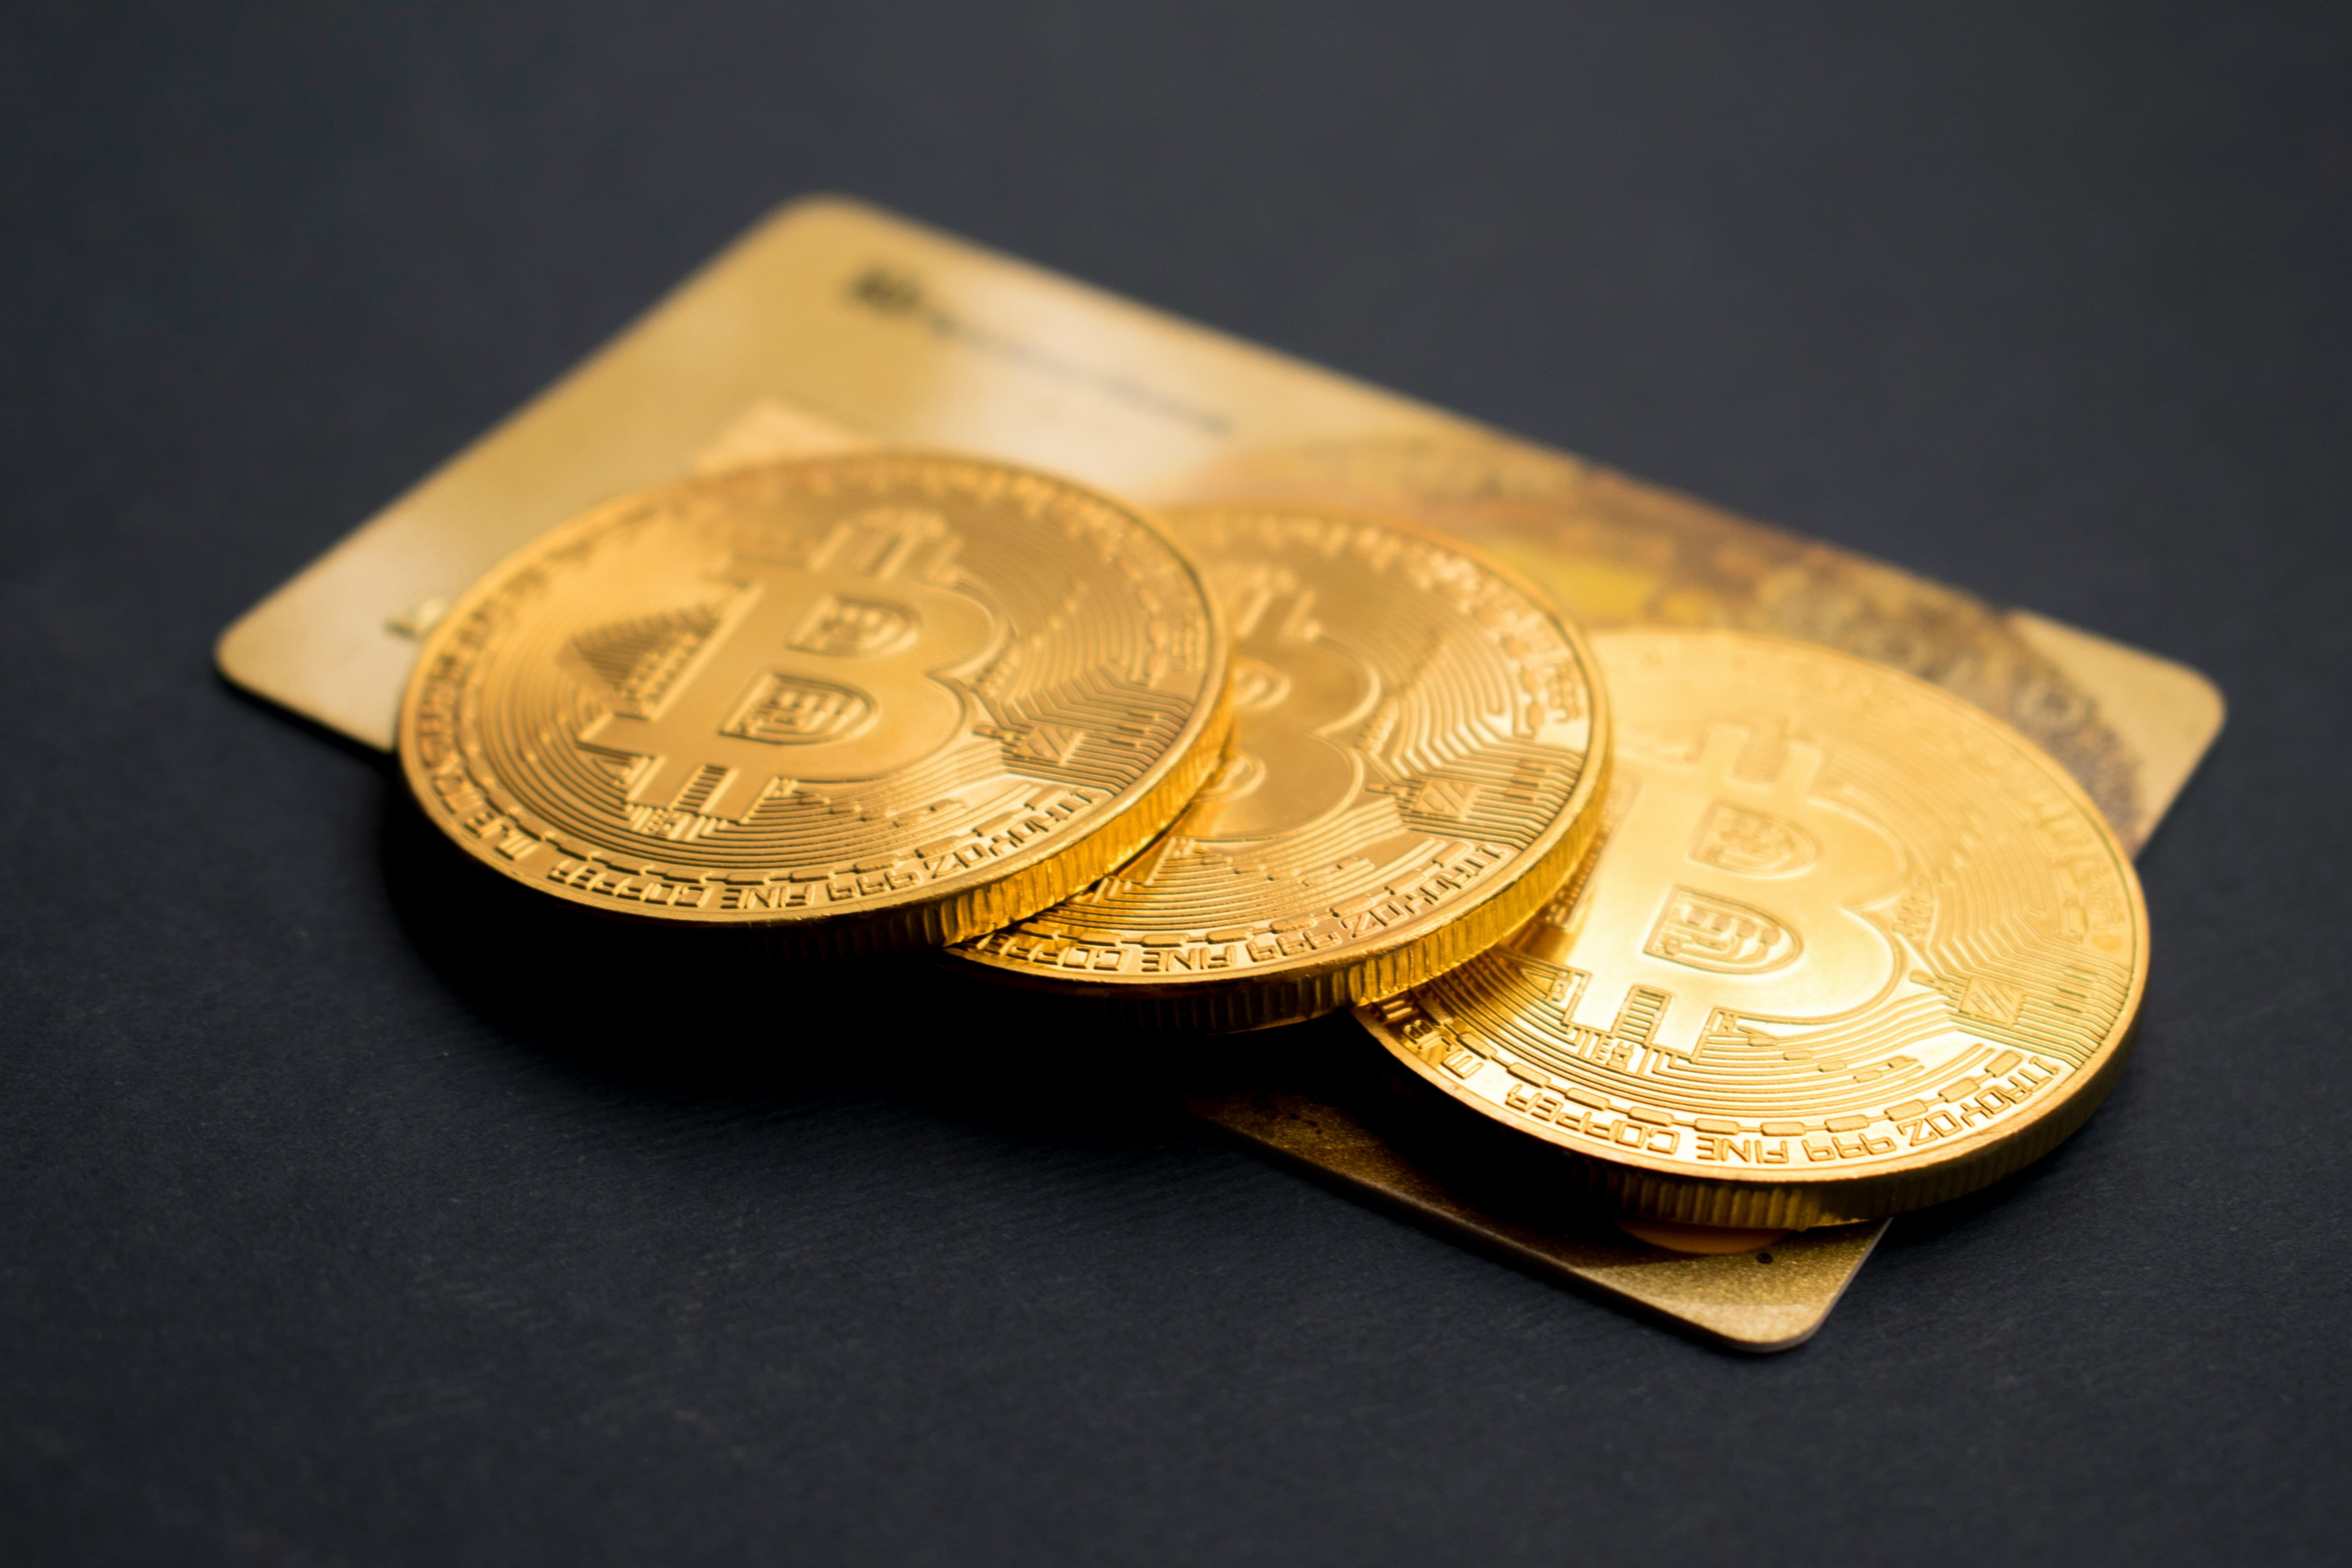
Crypto‑linked debit cards are moving from niche novelty to mainstream payment option, promising holders of Bitcoin, Ethereum and other digital assets a way to spend them at any merchant that accepts a standard Visa or Mastercard. While the convenience is appealing, prospective users need to understand the practical and regulatory nuances before signing up.
These cards typically connect to a user’s cryptocurrency wallet and automatically convert the chosen token into fiat currency at the moment of purchase. The conversion rate is supplied by the card issuer, which may use its own exchange or partner with third‑party platforms. Because the transaction happens in real time, merchants see a regular card payment while the user’s crypto balance is reduced accordingly.
Fees are a major differentiator among providers. Most issuers charge an upfront card‑issuance fee, a monthly maintenance charge, and a percentage‑based markup on each conversion from crypto to fiat. Additional costs can arise from ATM withdrawals, foreign‑currency transactions, and expedited card delivery. Users should scrutinize the fee schedule, as the cumulative expense can erode the perceived advantage of using crypto for everyday spending.
Regulatory compliance adds another layer of complexity. Card services must adhere to anti‑money‑laundering (AML) and know‑your‑customer (KYC) rules, meaning users will need to submit identity documents before activation. Some issuers are licensed as money‑transmitters or e‑money institutions, offering a degree of consumer protection, while others operate in less‑regulated jurisdictions, exposing users to higher legal and security risks. Moreover, the inherent price volatility of cryptocurrencies means the fiat value of a balance can fluctuate dramatically between the time of purchase and settlement.
Availability varies by country, and not all cards support the full spectrum of digital assets. Popular offerings often limit users to a handful of major coins such as Bitcoin, Ethereum, Litecoin and stablecoins pegged to the U.S. dollar. Transaction limits—both daily and per‑transaction—are imposed to mitigate fraud and comply with financial regulations, and they differ across providers.
For consumers weighing the pros and cons, crypto debit cards can simplify the use of digital assets without needing a separate exchange account for each purchase. However, the extra fees, potential for rapid value changes, and the need to trust a third‑party intermediary may outweigh the convenience for some. Traditional debit cards still offer broader acceptance, lower fees and established consumer safeguards.
Industry analysts expect the market for crypto‑backed payment cards to expand as regulators clarify the legal framework and as stablecoin adoption grows. Prospective users are advised to compare fee structures, read the fine print on conversion rates, and ensure the issuer holds appropriate licenses before committing to a card. By staying informed, they can decide whether the novelty of spending crypto aligns with their financial goals and risk tolerance.


Comments (0)
Be the first to comment.
Join the discussion